

By Toma Imirhe
The Bank of Ghana’s Monetary Policy Committee (MPC) has retained the Monetary Policy Rate (MPR) at 14%, extending its pause in the monetary easing cycle as it weighs renewed inflationary pressures against resilient economic growth – but bank treasurers are anticipating marginal falls in both lending and deposit rates over the next fortnight despite the MPC’s decision last week.
Related Stories
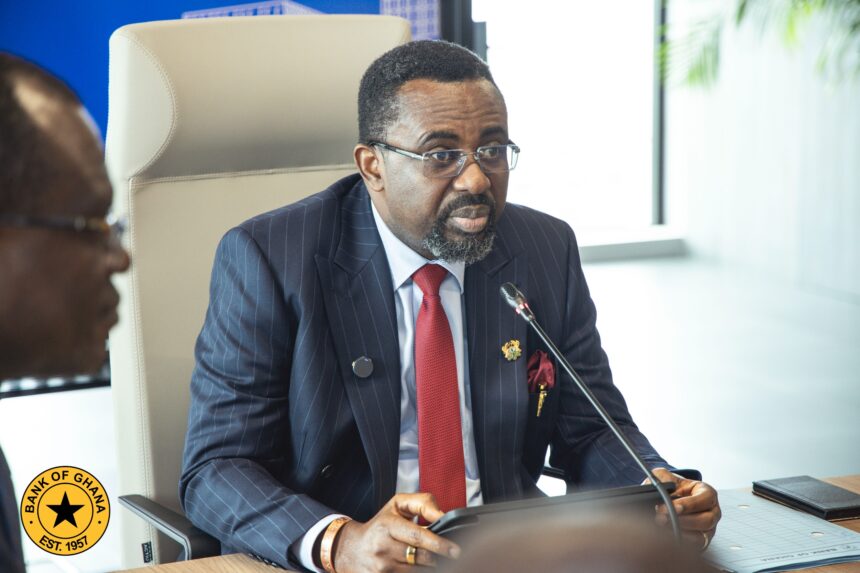
The unanimous decision, announced by central bank Governor and MPC Chairman Dr. Johnson Pandit Asiama on September 24 after the Committee’s 132nd meeting, represents the third consecutive MPC meeting at which the policy rate has been held at 14%. The Committee said the balance of risks to inflation and economic growth was “broadly balanced.”
The decision comes despite inflation remaining substantially below the Bank’s medium-term target range of 8% ±2 percentage points (this being a range of between 6% and 10%). Headline inflation increased from 4.6% in July to 5% in August, but the MPC said the rise was largely associated with utility tariff adjustments and higher crude-oil prices rather than a broad resurgence in underlying inflation.
Dr Asiama said the Bank’s assessment was supported by easing underlying pressures. Core inflation declined marginally to 4.2% in August from 4.3% in July, while inflation expectations across the surveyed groups – both businesses and households – also moderated.
Despite this, all the inflation expectations and core inflation measures are indicating a moderation in underlying inflation,” the Governor said.
The MPC nevertheless identified significant upside risks. These include further utility-price adjustments, higher petroleum prices and their potential pass-through into transport fares, a stronger US dollar associated with higher international interest rates, and disruptions to global supply chains arising from geopolitical tensions.
Against these threats, the Committee identified continued fiscal consolidation, improved food supply conditions and exchange-rate stability as important factors that could contain inflation.
Economic growth provided the other major argument for leaving the policy rate unchanged. Ghana’s economy remained resilient during the first half of 2026, with real GDP growth of 6% in the second quarter and private-sector credit growth rebounding to 35.5% (year on year) in August. The average bank lending rate had fallen to 15.9% from 24.2% a year earlier, demonstrating that the earlier monetary easing had already transmitted substantially into borrowing costs.
The external position also strengthened. The trade surplus reached US$8.85 billion during the first eight months of 2026, up from US$6.69 billion during the corresponding period of 2025, with exports rising to US$22.4 billion from US$17.9 billion.
Market interest rates to remain relatively stable… but marginal declines possible
The immediate implication of the 14% MPR hold is likely to be relative stability rather than another broad-based decline in domestic interest rates over the coming weeks.
Treasury-bill yields, particularly at the short end, are therefore likely to trade within a relatively narrow range as investors adjust to the message that the BoG is prepared to maintain its current stance while monitoring inflation and global developments. Longer-term government securities could remain more sensitive to fiscal financing requirements, inflation expectations and international bond yields than to the MPR alone.
For commercial banks, the decision should reinforce the current lending-rate environment rather than trigger a fresh, system-wide re-pricing. Competition for quality borrowers and deposits could nevertheless produce selective changes in loan and deposit rates as individual banks manage liquidity and margins. Although the retention of the MPR at 14% means any upcoming changes by commercial banks will be marginal rather than large, some banks can be expected to adjust selected loan and deposit rates over the next week or fortnight as they respond to movements in their own funding costs, the Ghana Reference Rate (GRR), Treasury-bill yields, liquidity conditions and competitive pressures.
The 14% rate also leaves borrowing conditions considerably easier than a year ago. The GRR’s decline has already been accompanied by reports of average lending rates around 15%, with some highly rated customers reportedly obtaining loans at 11–12.5%.
That creates an incentive for banks with excess liquidity or relatively low funding costs to cut selected lending rates rather than lose attractive customers to competitors.
Businesses therefore retain access to significantly cheaper credit than during the earlier tightening cycle, although banks’ assessment of borrower risk will remain important.
For households and businesses, the hold provides greater predictability for financial planning. Existing borrowers are unlikely to see a policy-driven jump in rates in the immediate term, while prospective borrowers can continue to benefit from the substantially lower lending-rate environment.
For investors, however, the decision reduces the immediate likelihood of another sharp fall in money-market yields. Pension funds, fund managers and other institutional investors may consequently continue balancing the relatively attractive liquidity and capital-preservation characteristics of Treasury securities against opportunities in longer-dated government and corporate instruments.
The central bank’s stance thus amounts to a pause rather than a reversal of the substantial easing undertaken since 2025. With inflation still below target but moving upward, and economic activity remaining strong, the MPC has opted to preserve policy space.
As Dr. Asiama put it, the Committee considered the risks to inflation and growth “broadly balanced” before unanimously retaining the MPR at 14%.
The outcome means that, for the next several weeks, Ghana’s money and capital markets are likely to be driven less by changes in the policy rate and more by inflation data, petroleum prices, exchange-rate movements, Treasury borrowing requirements and global interest-rate developments.