

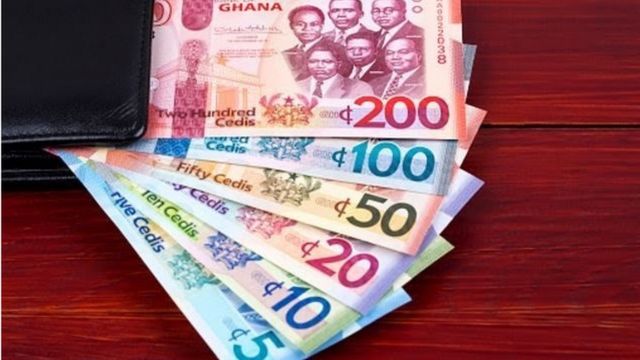
The Ghana cedi recorded the steepest maximum depreciation among African currencies monitored by the World Bank in the second quarter of 2026, weakening by nearly 10 percent between March and June, even as the government maintains that the currency will remain stable.
The development highlights the contrasting pressures on the cedi, which came under significant pressure following the escalation of the conflict in the Middle East, but subsequently recovered some of its losses.
Related Stories
According to the World Bank’s October 2026 Africa Economic Update, the cedi recorded the largest maximum weakening among the currencies tracked between March and June.
It was followed by the currencies of Lesotho, Namibia, South Africa and Eswatini, which each recorded maximum weakening of roughly 7 percent. The Seychelles rupee also weakened by almost 7 percent, while the currencies of the Democratic Republic of Congo and Uganda recorded maximum declines of about 6 percent and 5 percent, respectively.
The World Bank said currency depreciation was broad-based across the region.
Most countries with available daily exchange rate data recorded currency depreciations during the second quarter of 2026 relative to end-February, before the conflict intensified.”
The Bank said in seven of the 22 countries monitored, excluding the CFA franc zone, maximum depreciation exceeded 5 percent, with Ghana, the Democratic Republic of Congo, Seychelles and South Africa among the affected countries.
Energy shock puts pressure on cedi
The World Bank attributed the pressure on African currencies partly to the sharp rise in oil and energy prices following the escalation of the Middle East conflict.
Higher energy prices increased import bills, particularly for net energy-importing economies, raising demand for US dollars and putting pressure on foreign exchange positions.
Heightened geopolitical uncertainty also triggered a flight to safer assets in global financial markets, encouraging capital to move away from emerging and frontier economies.
The depreciation also increased the local-currency cost of servicing US dollar-denominated debt in countries with significant external obligations, adding to fiscal pressures.
Cedi recovers some ground
Despite recording the largest maximum weakening between March and June, the cedi recovered some of its losses by August.
The World Bank said much of the pressure on African currencies had eased by the end of August, with only 10 currencies remaining weaker than their end-February levels.
By end-August, however, much of this pressure had eased, with only 10 currencies remaining weaker than their end-February levels,” the Bank said.
The impact of the external shock was not uniform across Sub-Saharan Africa.
Countries heavily dependent on energy imports, with limited foreign exchange buffers and high debt-service burdens, experienced stronger pressure, while commodity-exporting economies generally proved more resilient.
South Africa, for instance, benefited from stronger demand for gold and platinum, which supported foreign exchange earnings despite heightened global risk aversion.
Oil exporters such as Angola and Nigeria also benefited from higher crude oil prices, which boosted export receipts and foreign currency inflows.
Government confident of stability
Despite the World Bank’s assessment of the cedi’s performance during the second quarter, Deputy Finance Minister Thomas Nyarko Ampem has expressed confidence that the local currency will remain stable.
Speaking at the National Conference on Housing and Finance, Mr Ampem said exchange-rate stability was particularly important for households financing their homes because it reduced uncertainty over the cost of meeting financial obligations.
Thankfully, under the competent leadership of His Excellency President Mahama and Dr. Cassiel Ato Forson, the cedi has been stable and it will continue to be stable. That is a big relief,” he said.
He stressed that households earning their income in cedis should not have to worry about exchange-rate movements when planning their finances.
A family should not need to forecast the exchange rate to know whether it can keep its home,” he added.
The Deputy Finance Minister said the government would also pursue measures aimed at reducing the cost and risks associated with housing delivery.
He argued that access to finance alone would not solve Ghana’s housing affordability challenges, pointing to the need for clear land ownership, realistic construction costs, reliable demand and workable infrastructure plans.
He further identified predictable local approval processes and serviced land as important conditions for attracting investment into the housing sector.